4 Things to Know Before Changing Insurance Companies
By: Linda Chapman, Retention – Executive
Executive Summary:
Changing insurance companies can help you save money, but a lower premium doesn’t always mean a better policy. Before switching, compare policy limits, deductibles, exclusions, endorsements, and claims service. Most importantly, don’t cancel your current insurance policy until your replacement coverage is confirmed and active. Understanding these four considerations can help you make an informed decision and avoid unnecessary coverage gaps.
Are you considering changing insurance companies? Maybe your premiums have increased, you’re frustrated with your current carrier’s customer service, or you’ve found a cheaper insurance quote. Whatever the reason, switching insurance companies can be a smart decision, but there’s more to consider than the price.
A lower premium could mean higher deductibles, reduced coverage limits, or missing endorsements that protect you against specific losses. Canceling your existing policy too early could also leave you without insurance when you need it most.
At Grimes Insurance Agency, we help clients compare insurance options and work through the details that can make or break a smooth insurance transition. We’ve seen firsthand why it’s important to look beyond the premium and understand the coverage and service you’re actually receiving.
Before you make a switch, here are four important things to consider.
1. Why are you considering changing insurance companies?
Before looking for a new insurance company, take some time to understand why you’re considering a change in the first place.
Insurance doesn’t fit everyone perfectly, and we’ve heard plenty of reasons why clients consider changing carriers. Some of the most common answers include:
- Increasing premium prices
- Inadequate coverage for their needs
- Inconsistent communication
- Disappointing customer service during a claim
While these are all valid reasons to explore other options, it’s important to understand what’s causing the problem before making the decision.
For example, if your insurance premium has increased, consider whether changes in the insurance market, claims activity, or your individual policy have contributed to the increase. A higher premium doesn’t automatically mean a different insurance company is a better fit.
On the other hand, if you’re consistently experiencing poor communication, or aren’t receiving the service you expect, exploring other carriers may make sense.
The first step is understanding what you want to improve. Do you need help personalizing your policy? Read about Grimes’ Approach to Personalized Insurance to learn how you can make your coverage fit better.
2. What should you compare before changing insurance companies?
If you find a cheaper quote, ensure that it’s a better deal before you make things official. We recommend comparing the policies themselves, not just the premiums. This looks like reviewing items such as:
- Coverage limits
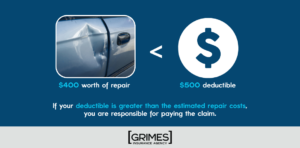
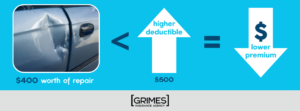
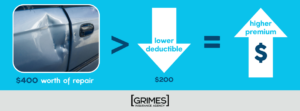
- Deductibles
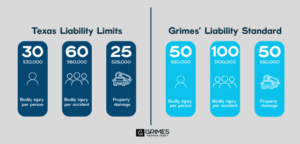
- Liability limits
- Exclusions
- Endorsements
- Policy fees and discounts
- Claims service and company ratings
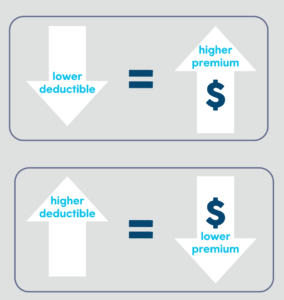
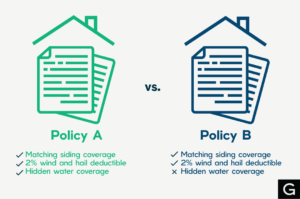
A lower premium can be a smart move if you’re getting comparable protection from a carrier that meets your needs. But if the savings come from lower limits, higher deductibles, or missing coverage, you may be taking on more risk than you realize.
For example, saving $1,000 a year on your homeowner’s policy could be worthwhile if the coverage is comparable. However, what happens if the new insurance company doesn’t offer an important endorsement you currently have, such as hidden water leakage and seepage coverage?
That missing protection could make the potential savings less attractive if you experience a loss that would have been covered under your previous policy.
When comparing, the goal is to find the right balance between price, coverage, and service. Simply looking for a cheaper policy doesn’t guarantee the right move.
How should you evaluate an insurance company’s claims service and ratings?
Price and coverage aren’t the only things that matter when choosing an insurance company. You should also consider how the carrier handles claims and what its financial and consumer reputation looks like.
After all, insurance is something you purchase to help protect yourself financially when something unexpected happens. You want confidence that your insurance company will respond appropriately when you need to use your coverage.
At Grimes Insurance, we’ve seen how much these details can matter. In one client’s case, a sewer backup flooded their home from the alley.
Because the backup didn’t begin on her property, her (SafeCo) policy wouldn’t initially cover the claim. Instead, the incident was considered a city responsibility. However, when the city denied her claim, we alerted her carrier.
SafeCo stepped in and ultimately agreed to pay her $25,000 claim. The carrier also helped her pursue the matter with the city.
This experience illustrates why claims handling matters in addition to price. Not all carriers handle similar claims the same way. Coverage depends on the policy language, applicable endorsements, the facts of the loss, and the insurer’s claim determination.
How do you review an insurance company’s ratings?
Several resources can help you research an insurance company’s financial strength, complaint history, and reputation.
One useful resource is the National Association of Insurance Commissioners (NAIC) Consumer Insurance Search tool, which provides information to help consumers research insurance companies, including complaint information and licensing details.
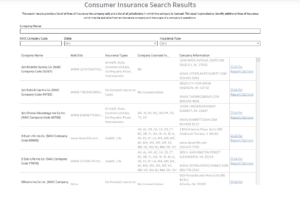
The Insurance Information Institute also recommends the following resources when comparing:
- A.M. Best Company
- Fitch Ratings
- Kroll Bond Rating Agency (KBRA)
- Moody’s Investor Services
- Standard & Poor’s Insurance Ratings Services
3. When should you cancel your existing insurance policy?
If your comparison leads you to switch companies, DO NOT cancel your existing company’s insurance policy until your replacement coverage is in place.
This is one of the most important steps in the switching process. A quote is not the same as an active policy, and an application may still be subject to underwriting requirements or final approval.
If you cancel your existing policy before your new coverage begins, you risk falling into an insurance lapse. If a covered event occurs during that period, you’d be required to pay for the loss yourself.
What is an insurance lapse?
An insurance lapse occurs when your existing policy ends and replacement coverage is not active for a period of time. Even a short gap matters, potentially affecting your ability to obtain insurance or the price you’re offered later.
Lapsed insurance is extremely common when policyholders change companies. It can take time for an insurance policy to be bound with a new carrier, and cancelling your old policy before it’s ready can leave you uninsured.
How can you avoid a coverage gap when changing insurance companies?
To avoid this mix-up, stay in constant communication with your agent and don’t cancel until your new coverage is verified.
Before cancelling your current insurance, confirm:
- The new insurance carrier has accepted your application
- All underwriting requirements have been completed
- You understand the final premium, deductibles, limits, and exclusions
- You have written, verified confirmation of the new policy and its effective date and time
At Grimes, we get that insurance timelines can get confusing, but you don’t have to face them alone. We’ll help you coordinate the transition so you know when your new policy is active and it’s appropriate to cancel the old one. If you’re considering an insurance company change, call our office to connect with an agent before submitting a cancellation request.
4. How do you change your insurance company?
Changing insurance companies is easier when you follow a clear sequence. Each step has a purpose, and completing them in the right order reduces the risk of missed payments, incorrect policy details, or lapsed coverage. After a conversation with your agent,
- Review your current policy
- Gather accurate information for quotes
- Compare policies
- Complete your new application and any required payment
- Confirming your new coverage is active
- Cancel your old policy
Following these steps can help you make a smooth insurance transition while maintaining the protection you need.
Grimes Insurance can help you change insurance companies
Changing insurance companies can be a worthwhile decision, especially if you’re able to find better coverage, service, or pricing elsewhere. But before making the switch, take the time to understand why you’re leaving, compare the actual policy details, research the new carrier, and coordinate your cancellation dates.
Remember, the goal isn’t about finding a cheaper insurance policy. It’s finding the right protection at a price that makes sense for you.
At Grimes Insurance Agency, we understand how important it is to feel confident in your insurance coverage. With a network of 100+ insurance carriers, we’ve helped clients navigate policy changes, compare carriers, and work through the details.
If you’re considering changing insurance companies, call our office to connect with an agent. We’ll help you evaluate your options, understand the differences between policies, and determine what makes the most sense for your insurance needs. Or, if you’re still debating, learn more about coverage gaps and learn How to Tell if You’re Underinsured.
Frequently Asked Questions About Changing Insurance Companies
Can you switch insurance companies at any time?
In many cases, you can change insurance companies before your existing policy expires. However, your current policy’s cancellation terms may affect the process, including whether cancellation fees or other charges apply.
Review your policy and speak with your insurance agent before making a change.
Will you receive a refund if you cancel your insurance policy early?
You may receive a refund for the unused portion of your premium if you cancel your policy before its expiration date. However, the amount depends on your policy’s cancellation terms and whether any fees or other charges apply.
If your homeowners insurance premium was paid through an escrow account, you may have additional questions about what to do with your refund. Read our article, Got a Refund Check from Your Old Insurance Company?, to learn what happens to that money and whether it needs to go back to your mortgage company.
Ask your current insurance company how it calculates refunds before canceling.
Does changing insurance companies affect your insurance history?
Switching insurance companies doesn’t automatically erase your previous insurance history. New insurers may consider factors such as prior coverage, claims history, and previous lapses when evaluating your application.
Maintaining continuous coverage is important when transitioning between carriers.