
What Lubbock Home Insurance Covers (And What it Doesn’t)
By: Niki Saavedra, Director of Operations
Executive Summary:
A standard homeowners insurance policy typically covers your home, belongings, liability, and additional living expenses after certain covered losses. It generally does not cover flooding, gradual damage, normal wear and tear, or certain other exclusions.
For Lubbock and South Plains homeowners, wind and hail deductibles, roof coverage, and water-related losses deserve particular attention.
Do you know exactly what your home insurance policy covers, or what could leave you paying thousands out of pocket?
If a hailstorm damages your roof, a pipe bursts, or a sewer backs up into your home, would your policy pay for the damage? The answer depends on what caused the loss, what your policy covers, and which exclusions or endorsements apply.
At Grimes Insurance Agency, we’ve reviewed home insurance policies for West Texas homeowners since 1948. For homeowners in Lubbock and the surrounding South Plains communities, understanding those details can be especially important when severe weather or other unexpected losses put your coverage to the test.
By the end of this article, you will know:
- What a standard home insurance policy covers
- What a home insurance policy excludes
- Which protections West Texas homeowners should consider
What Does Home Insurance Typically Cover?
A standard homeowners policy, such as an HO-3, typically provides several types of protection. Let’s break down what they typically include:
Home structure protection
Dwelling coverage helps pay to repair or rebuild your home when it is damaged by a covered peril. Depending on the policy, covered events can include:
- Fire
- Lightning
- Windstorm
- Hail
- Vandalism
- Theft
Personal property protection
In the event of a covered peril, personal property coverage can protect belongings inside your home, such as:
- Furniture
- Clothing
- Appliances
- Electronics
High-value belongings, like jewelry, firearms, art, and collectibles, may have special limits, so a standard policy might not be enough. Most valuable items require additional policy coverage, like scheduling your valuables under an endorsement. Be sure to check your policy thoroughly to ensure your high-value items remain protected.
Liability protection
If someone were to become injured on your property and you’re legally responsible, liability coverage can help pay for legal defense costs, medical bills, and judgments.
Standard policies typically include liability coverage of $100,000 to $300,000. Higher limits or a personal umbrella policy may make sense for homeowners with significant assets.
Additional living expenses coverage
If a covered loss makes your home temporarily uninhabitable, additional living expenses coverage becomes extremely helpful. This coverage can help pay for temporary housing, meals, and other qualifying costs while repairs are completed. Generally, this coverage is often capped at 20 to 30 percent of your dwelling limit.
What does home insurance typically NOT cover?
Some of the biggest coverage surprises involve losses that require separate insurance or an endorsement.
Does home insurance cover flooding in Lubbock?
Generally, a standard homeowners policy excludes outside flooding from a natural event. Flood damage requires a separate policy through the National Flood Insurance Program (NFIP) or a private carrier to be covered.
In most low flood risk areas like West Texas, understanding flood insurance doesn’t seem necessary. However, don’t be quick to dismiss it. In fact, 29% of NFIP flood claims come from areas without a flood risk.
It’s important to distinguish flooding from other types of water damage. For example, a sudden water damage claim from a burst kitchen pipe or sewer backup is treated differently than water entering your home from the outside.
Does Home Insurance Cover Sewer Backup?
A sewer backup incident is a major (and literal) stinkfest and can cause thousands of dollars in damage to finished spaces and belongings. However, water backup coverage is only available through a policy endorsement or rider.
You should consider adding sewer backup coverage to your homeowners policy if:
- You live in an older home with aging septic and pipes
- You have a sump pump and/or a basement
- You have nearby trees with deep roots that could affect your plumbing system
Does Home Insurance Cover a Home-Based Business?
A standard homeowners policy provides very little to no coverage for a home-based business, typically offering only $2,500 of coverage for business equipment. Without additional coverage or endorsements, items like your business inventory, liability, or separate work areas could be at risk.
If you’re looking to insure your business, Grimes can help you find the right options. Feel free to call our office to discuss your coverage with our commercial insurance team.
Does home insurance cover gradual damage claims?
Standard home policies only cover sudden, accidental damage from specific perils. Because of this, damage that develops over time is excluded. This includes issues like:
- Slow leaks
- Foundation settling
- Mold growth
- Pest damage
- Normal wear-and-tear
What coverage gaps should Lubbock homeowners watch for?
For homeowners in Lubbock and across the South Plains, wind and hail deductibles and roof settlement deserve particular attention.
Wind and hail deductibles
Your policy may include a separate wind and hail deductible that applies to covered storm damage.
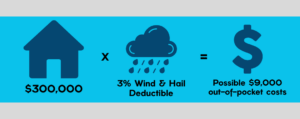
For example, if your $300,000 home has a 3% wind and hail deductible, you could have $9,000 in out-of-pocket costs before your insurance coverage applies. And that’s not a situation anyone wants to be in.
We’ve seen this play out firsthand. In our experience, some carriers will lower a policy’s wind and hail deductible during storm season, but only if the client calls in to request the change first.
When a storm is actually in the forecast, clients often call in a panic trying to make that switch, only to learn the change won’t take effect for 24 hours. They’re stuck at the higher deductible right when they need the lower one most.
Knowing your deductible ahead of time, rather than scrambling the night before a storm, can make a real difference in what you pay out of pocket.
Replacement Cost vs. Market Value
With the high amount of hail-related roof claims we see in our area, you should also find out how much your roof would be settled for after a covered loss.
Replacement cost coverage can help pay the cost to replace a damaged roof, subject to the policy terms and deductible. Actual cash value accounts for depreciation.
For example, if replacing a roof costs $12,000, depreciation could significantly reduce the amount paid under an actual cash value settlement.
Before you file your next roof claim, ask your agent how your roof is covered to avoid any costly surprises.
How can you find coverage gaps before a claim?
Before your next renewal, ask these three questions:
- Does my dwelling coverage reflect my home’s current replacement cost?
- Do I have sewer backup coverage, and does my home need it?
- What kind of wind and hail deductible does my home have? Should I lower it during hail season?
- Would my roof claim be settled at replacement cost or actual cash value?
Discussing these questions with your insurance agent can help you identify important coverage gaps before a storm, water damage, or another claim occurs.
Grimes can help you review your homeowners policy
A general homeowners policy protects your home’s structure and belongings, covers liability, and provides additional living expenses if your home becomes uninhabitable. However, knowing what your policy excludes can be just as important as knowing what it covers.
Claims from flood, water backup, and gradual issues are not protected by a standard policy and require additional coverage or endorsements. For Lubbock homeowners, understanding your wind and hail deductible, roof settlement, water coverage, and other exclusions can help prevent expensive surprises.
At Grimes Insurance Agency, we’ve helped West Texans understand their coverage since 1948. If you own a home in Lubbock or the surrounding South Plains, feel free to call our office and connect with an agent. We can help you review your policy, understand what it protects, and find the right coverage fit for your home.
Or, if you’re curious about what it takes to get the right protection, read What to Expect When Shopping for Home Insurance With Grimes. That way, you can learn how our process works before you’re ready to make a decision.


